
The runway for equities – are markets settling into a new pace?
The narrative surrounding global equities is subtly shifting. Once dominated by momentum-driven optimism, especially for artificial intelligence (AI), today’s market discussions instead focus on structural frictions.
The most bullish equity strategist of note is U.S. researcher Edward Yardeni, whose Fabulous Earnings Momentum (FEMO) thesis has driven his estimate for the S&P500 to reach 8,400 – 10 per cent higher than where we are today. Originally, this target was slated for the end of 2026, but now Yardeni has moved it to the middle of next year.
He notes the recalibration isn’t a reassessment of FEMO, but an acknowledgement of macro headwinds that limit immediate price to earnings (P/E) multiple expansion.
The multiple compression paradox
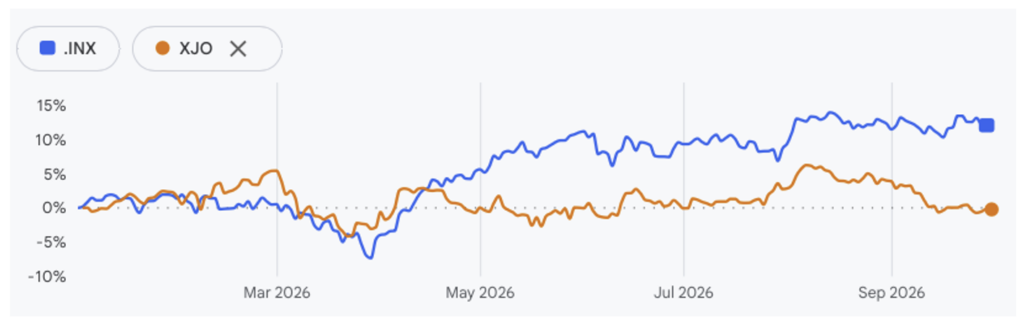
And right on cue, equity indices are stalling near current levels despite record U.S. corporate profitability. Why? Investor psychology.
Figure 1. YTD Performance, S&P500 (.INX) & S&P/ASX200 (XJO)
Source: Google Finance
Corporate earnings across large-cap growth businesses in the U.S. continue to beat consensus expectations, delivering healthy revenue growth and resilient margins, and during the later stages of the market advance, equity prices were propelled primarily by a fear of missing out (FOMO).
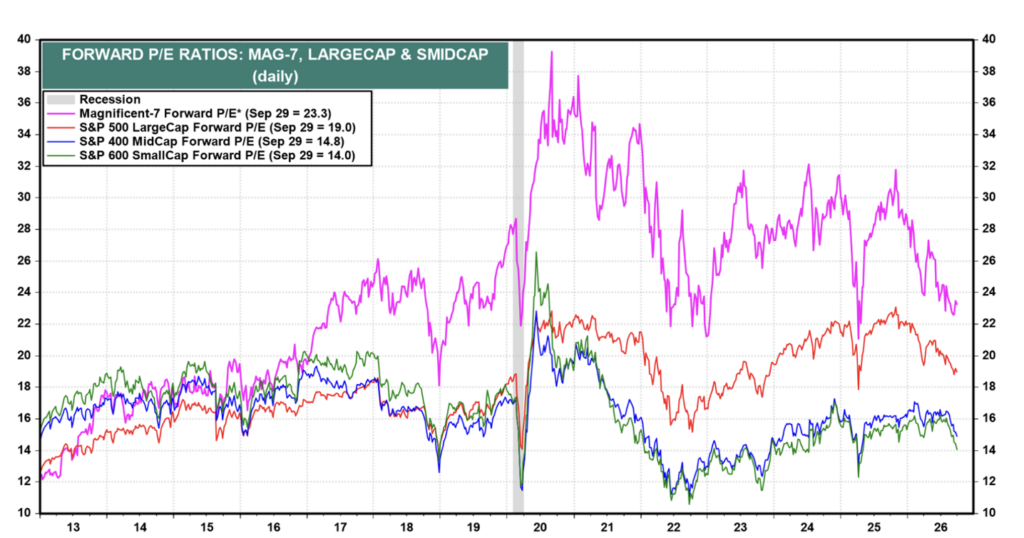
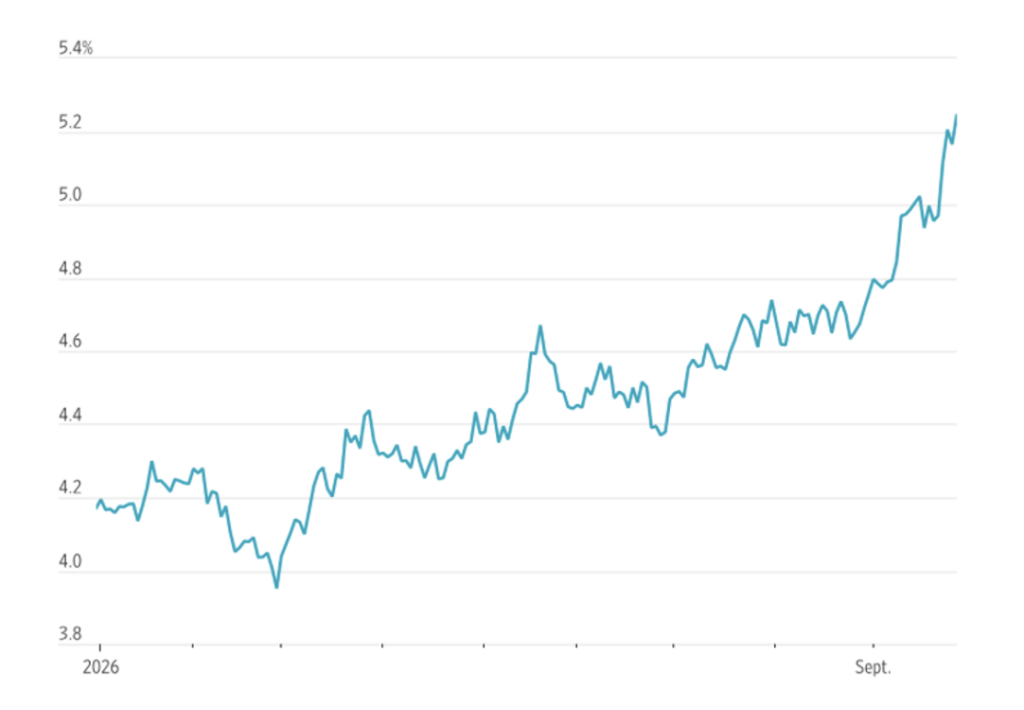
Yet, despite the operational success, earnings multiples are contracting. Investors, confronted by rising and increasingly attractive bond yields, geopolitical uncertainty, and changing liquidity, are simply refusing to pay ever-higher multiples for forward earnings, especially AI earnings that aren’t guaranteed.
Consequently, price-to-earnings (P/E) multiples are shrinking even as underlying earnings increase.
Figure 2. Forward P/E ratios
Source: LSEG Datastream and Yardeni Research, and Standard & Poor’s.
According to Yardeni’s latest prognostication, the probability of a smooth, non-inflationary “Roaring 2020s” growth trajectory has declined from 80 per cent to 70 per cent, while the probability of a stagflationary or macro-adverse outcome has risen from 20 per cent to 30 per cent.
The Federal Reserve’s dilemma
The primary force driving multiple compression stems from energy markets and rising geopolitical risk. Renewed conflict in the Middle East has injected renewed volatility into global crude markets, creating persistent upward pressure on energy prices.
Higher crude costs ripple rapidly across international supply chains, increasing fuel costs and instantly raising transport overhead across freight networks. At the same time, higher machinery operating costs and fertiliser prices inflate production budgets for consumer essential goods. Finally, intermediate input costs pass through to final consumer prices, generating sticky core inflation metrics that resist central bank targets.
Meanwhile, wage pressures seem to be building too. When labour demand outstrips labour supply, employers have to compete more aggressively for workers, resulting in faster wage growth. Yardeni points out that former Fed Chair Jerome Powell’s framework for assessing labour-market tightness compares labour demand, using the sum of household employment plus job openings, with the labour force. By that measure, demand has slightly exceeded supply for four straight months, the longest such streak since March 2023.
All of this complicates central bank strategy and the Federal Reserve is increasingly expected to maintain a prolonged tightening bias. Indeed, money markets have begun pricing in up to two additional rate hikes before year-end to keep long-term inflation expectations anchored.
Figure 3. U.S. 10 year treasury yields
Source: WSJ
The Bank of Japan and the unwind of global leverage
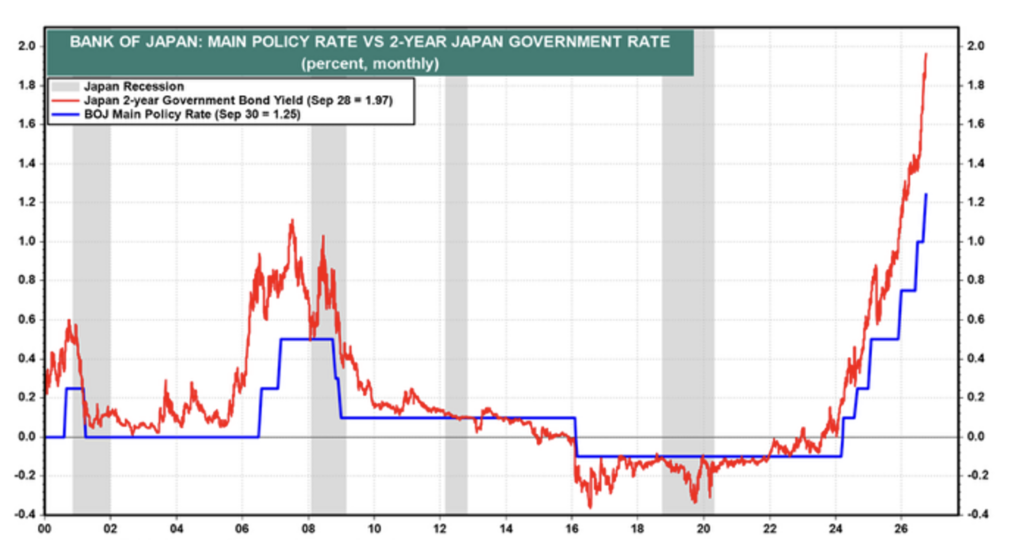
Compounding these U.S. interest rate dynamics is a pivot in global capital flows driven by the Bank of Japan.
For decades, international financial markets relied heavily on the yen carry trade. Institutional asset managers, hedge funds, and global arbitrage desks systematically borrowed capital in Japan at near-zero rates and deployed those funds into higher-yielding global debt and risk assets.
Figure 4. Japanese interest rates
Source: LSEG Datastream and Yardeni Research. Bank of Japan
Now, as the Bank of Japan raises its policy benchmark rate and signals a continued trajectory toward monetary normalisation, the rationale for the Yen Carry Trade is eroding. As borrowing costs in Japan rise, foreign-deployed capital is repatriated. In other words, U.S. bonds are sold off, with the proceeds used to repay the Japanese loans. This pulls a major source of liquidity and leverage out of global sovereign bond markets and risk assets.
Implications
While strong earnings provide a firm footing for equity markets, the ongoing Middle East conflict means associated energy cost increases and volatility will persist. This, along with higher interest rates and tightening global liquidity, should cap immediate equity price expansion. Therefore, structurally, the trajectory for equities remains positive, but at best, investors will need more patience and should expect a longer, more volatile road to gains.

Roger Montgomery is the Founder and Chairman of Montgomery Investment Management. Roger has over three decades of experience in funds management and related activities, including equities analysis, equity and derivatives strategy, trading and stockbroking. Prior to establishing Montgomery, Roger held positions at Ord Minnett Jardine Fleming, BT (Australia) Limited and Merrill Lynch.
He is also author of best-selling investment guide-book for the stock market, Value.able – how to value the best stocks and buy them for less than they are worth.
Roger appears regularly on television and radio, and in the press, including ABC radio and TV, The Australian and Ausbiz. View upcoming media appearances.
This post was contributed by a representative of Montgomery Investment Management Pty Limited (AFSL No. 354564). The principal purpose of this post is to provide factual information and not provide financial product advice. Additionally, the information provided is not intended to provide any recommendation or opinion about any financial product. Any commentary and statements of opinion however may contain general advice only that is prepared without taking into account your personal objectives, financial circumstances or needs. Because of this, before acting on any of the information provided, you should always consider its appropriateness in light of your personal objectives, financial circumstances and needs and should consider seeking independent advice from a financial advisor if necessary before making any decisions. This post specifically excludes personal advice.


