
The Fallacy of Composition
In the stock market, equity analysts are typically bottom-up researchers. That means they start their analysis of an individual company with specific financial metrics and fundamentals, rather than macroeconomic trends or overall industry outlooks.
Instead of starting with Gross Domestic Product (GDP) growth, interest rates, or sector tailwinds, a bottom-up analyst focuses on a company’s internal strengths, business model, and valuation.
A problem arises because modelling a specific company using the bottom-up approach occurs in a vacuum.
Analyst A assumes Company A will take market share away from Company B. Analyst B assumes Company B will hold its market share and grow sales by 10 per cent. Analyst C assumes Company C will benefit from lower commodity prices, while Analyst D assumes the commodity producer will raise prices.
An issue occurs because, individually, each model looks reasonable to its author and to the investors who read the report. But when you sum up all the bottom-up consensus estimates, you arrive at an aggregate revenue or earnings figure that, for example, implies GDP would have to grow by 15 per cent – an economic impossibility.
Some call it the ‘Micro-Macro Aggregation Disconnect’. In formal economics, this issue is known as the Fallacy of Composition. It’s the error of assuming that what is true for a part is automatically true for the whole, and it happens when bottom-up consensus fails the top-down sanity check.
A past example
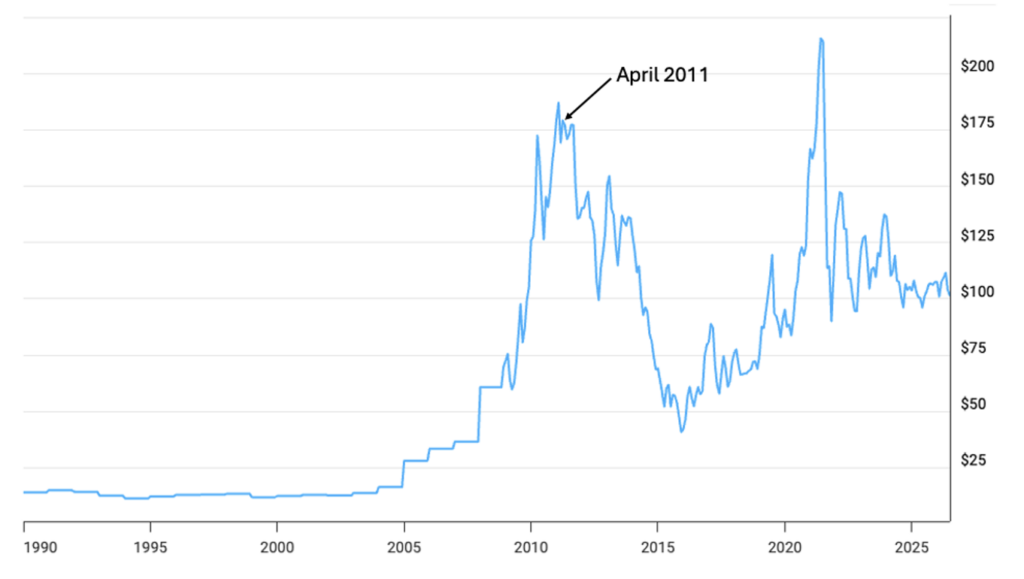
Fifteen years ago, in 2011, a commodity boom in iron ore saw BHP’s share price hit $40 for the first time. It was 8 April 2011. There was great excitement surrounding Australia being the ‘lucky’ country yet again. Peter Richardson, Morgan Stanley’s then global metals chief economist, put forward a strong investment case for the “crucial” steelmaking commodity.
By contrast, on April 11 that year we published a blog, Will China demand Iron… or…?, in which we predicted iron ore prices would decline, ending the commodity boom and causing buoyant share prices to fall.
The reason for our bearish view was that in 2010-11, world iron ore production grew 8.1 per cent or 227mt to 2.8bt. Analysts for BHP and FMG began assuming similar growth levels for 2011-12 – in a classic supply response to the record iron ore prices. BHP production was forecast to grow by 20 per cent, Return On Investment (ROI) by 30 per cent, FMG – 25 per cent. Iron ore production was expected to grow to 3,037bt, an increase of 237mt.
Individually each company’s future looked bright. But collectively, we estimated that by 2015 “two entire Pilbara regions (700mt) in supply terms will come onto the market. It’s a far stretch to expect China to absorb 420mt (60 per cent) of that. The impact we expect is pressure on iron ore prices.”
And that’s what happened.
Figure 1. Global iron ore price, $U.S./metric ton
Source: Macrotrends
Today
Nothing much has changed on Wall Street today. Equity analysts still work in their own echo chambers or silos, and it’s not uncommon to add up all their forecasts and arrive at an absurdity.
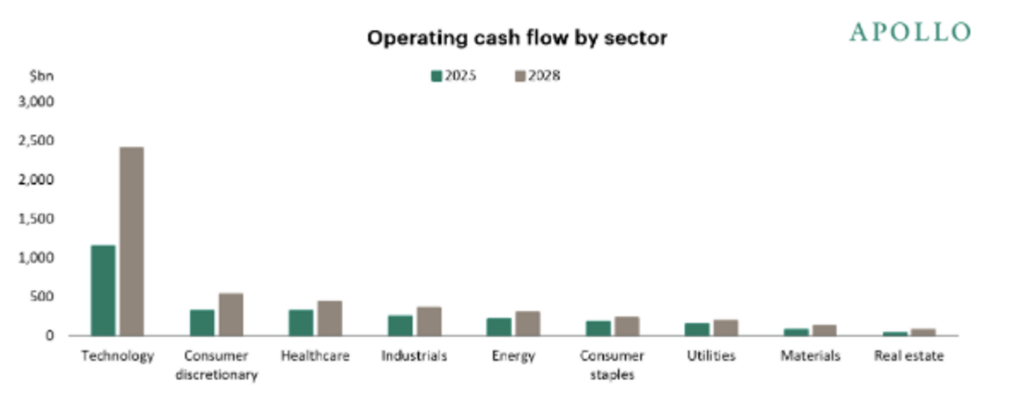
Take, for example, the technology analysts. By 2028, they expect operating cash flow to more than double to more than US$2.4 trillion.
For companies to generate operating cash flows, they need customers to pay them. Those downstream customers must generate enough revenue and cash flow to pay the upstream suppliers. But analysts covering the other sectors in the S&P 500, which are the technology companies’ customers, expect those companies to add far less operating cash flow.
In other words, we’re seeing another example of the Fallacy of Composition problem. One of the sectors analysts are very wrong. The tech analysts are betting on an explosion of demand for artificial intelligence (AI) services, while the analysts covering the tech companies’ customers don’t.
So, to the tech analysts who aren’t aware of the Fallacy of Composition, ask yourselves: where is all this cash going to come from (Figure 2)?
Figure 2. Tech cash flow to magically soar.
Source: Apollo Global Management, FactSet

Roger Montgomery is the Founder and Chairman of Montgomery Investment Management. Roger has over three decades of experience in funds management and related activities, including equities analysis, equity and derivatives strategy, trading and stockbroking. Prior to establishing Montgomery, Roger held positions at Ord Minnett Jardine Fleming, BT (Australia) Limited and Merrill Lynch.
He is also author of best-selling investment guide-book for the stock market, Value.able – how to value the best stocks and buy them for less than they are worth.
Roger appears regularly on television and radio, and in the press, including ABC radio and TV, The Australian and Ausbiz. View upcoming media appearances.
This post was contributed by a representative of Montgomery Investment Management Pty Limited (AFSL No. 354564). The principal purpose of this post is to provide factual information and not provide financial product advice. Additionally, the information provided is not intended to provide any recommendation or opinion about any financial product. Any commentary and statements of opinion however may contain general advice only that is prepared without taking into account your personal objectives, financial circumstances or needs. Because of this, before acting on any of the information provided, you should always consider its appropriateness in light of your personal objectives, financial circumstances and needs and should consider seeking independent advice from a financial advisor if necessary before making any decisions. This post specifically excludes personal advice.


